The firm that built financial discovery
Most family law firms subpoena the bank and wait. We wrote the method that doesn't — and published the brief that puts it in front of a judge.
King and Snohomish Counties, Washington · Divorce, legal separation, and property division
We built it
The authorized retrieval method published at civilrule26.com
We briefed it
A model memorandum on proportionality, burden, and authentication
An engineer wrote it
Eleven years building regulated data systems, and a U.S. patent, before he practiced family law
Three ways a paper production fails
Washington requires complete financial disclosure in every dissolution involving property or support. Meeting it with a stack of statements leaves three holes, and all three favor whoever assembled the stack.
The accounts nobody listed
A party produces statements for the accounts they choose to name. The account they forgot — or chose not to name — produces nothing, and nothing in the production announces its absence.
The months that quietly went missing
Twenty-two monthly PDFs look complete until someone notices two are missing. Gaps in a paper production are invisible unless a person checks every cycle by hand.
The balance nobody can actually prove
Statements close at month end. Separation dates do not. A balance on the 9th has to be derived from transactions — or the court is asked to accept an interpolation.
What we do instead
The account holder authorizes a read-only, revocable retrieval at their own financial institution, through that institution's own login. No password is shared with anyone. What comes back is not a monthly summary but the transaction record itself — every posting date, every amount — with a timestamp for when it was pulled.
That changes what can be said about the record afterwards. A balance can be computed for any day inside the window, including the one the law actually cares about. The accounts held at each authorized institution are enumerated, including ones nobody thought to ask about. And the retrieval can be run a second time, so a discrepancy between what was produced and what the institution holds becomes visible instead of invisible.
Where the other side will not authorize, the traditional tools still apply — and the refusal is now on the record. The model brief we published is written for exactly that motion.
When this matters most
- Business owners and closely held interests
- High-asset and multi-institution estates
- Suspected undisclosed or transferred accounts
- Tracing separate property through commingled funds
- Post-separation spending and dissipation claims
- Any matter where the other side has been slow to disclose
Why we can do this and most firms cannot
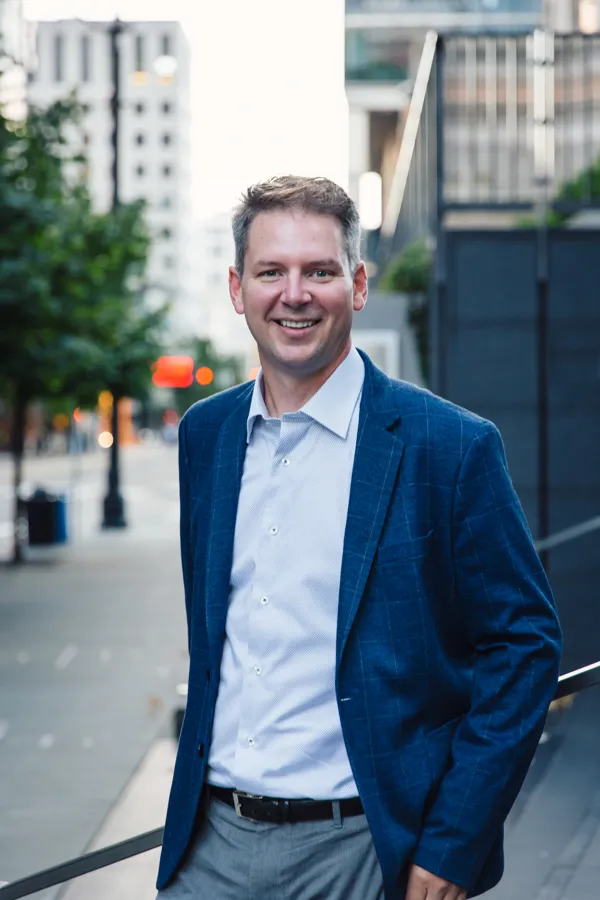
John N. Phillips holds a computer science engineering degree from Ohio State and spent eleven years building the systems that move regulated records between institutions: HIPAA and X12 transaction systems at Premera Blue Cross and Highmark, electronic medical records at IDX Systems, an ontology platform at GE Healthcare, and the core data ingestion tooling at Caradigm. He holds a U.S. patent.
He then graduated summa cum laude, on Law Review and Moot Court, externed at the U.S. Patent and Trademark Office and the Federal Trade Commission, ran his own intellectual property firm for four years, and moved to family law at McKinley Irvin in 2023. He designed and built the retrieval method himself, and wrote the memorandum that puts it before a court.
Financial discovery is not a service we bought. It is the thing we made.
Read John's backgroundBring us the matter where the numbers have to be right
We take King and Snohomish County dissolutions, and we start with a working consultation — a real meeting about your case, not a sales call.
New Client ApplicationPrefer to read first? How financial discovery works in Washington covers the disclosure rules and what a complete record requires.